Accounting Software
Security Deposit Accounting: How to Handle Deposits the Right Way (2026)
Matt Valentine•November 3, 2026
Here's the mistake that costs landlords the most: treating a security deposit like money they've earned.
It's an easy mistake to make. The deposit hits your bank account, the balance goes up, and it feels like income. But it isn't. That money belongs to the tenant. You're just holding it, and you may have to give all of it back.
Landlords who book deposits as income are the same ones who discover at move-out that the deposit quietly got absorbed into a roof repair eight months ago. Now the money isn't there, the tenant wants it back, and depending on the state, they may be entitled to two or three times the amount for the mishandling.
Security deposit accounting isn't complicated, but it is exacting. This guide covers how to record deposits correctly, where to hold them, and how to handle deductions and refunds without creating legal exposure.
The single most important concept in security deposit accounting is this: a deposit is a liability.
When a tenant hands you a security deposit, that money doesn't belong to you or the property owner. It belongs to the tenant until the lease ends and you have documented, lawful reasons to retain some or all of it. In accounting terms, that makes it a liability, an obligation to return money, which sits on your balance sheet, never on your income statement.
The IRS draws the same line: a security deposit you intend to return is not income when you receive it. It only becomes income if and when you keep part of it (for unpaid rent or damages) under the lease terms.
This distinction matters for more than clean books. Misclassifying deposits as revenue inflates your reported income, distorts owner distribution reports, and can create serious legal exposure. It's the kind of error that looks minor until it becomes a lawsuit.
The accounting itself is simple once you understand the liability concept. It comes down to a few standard entries.
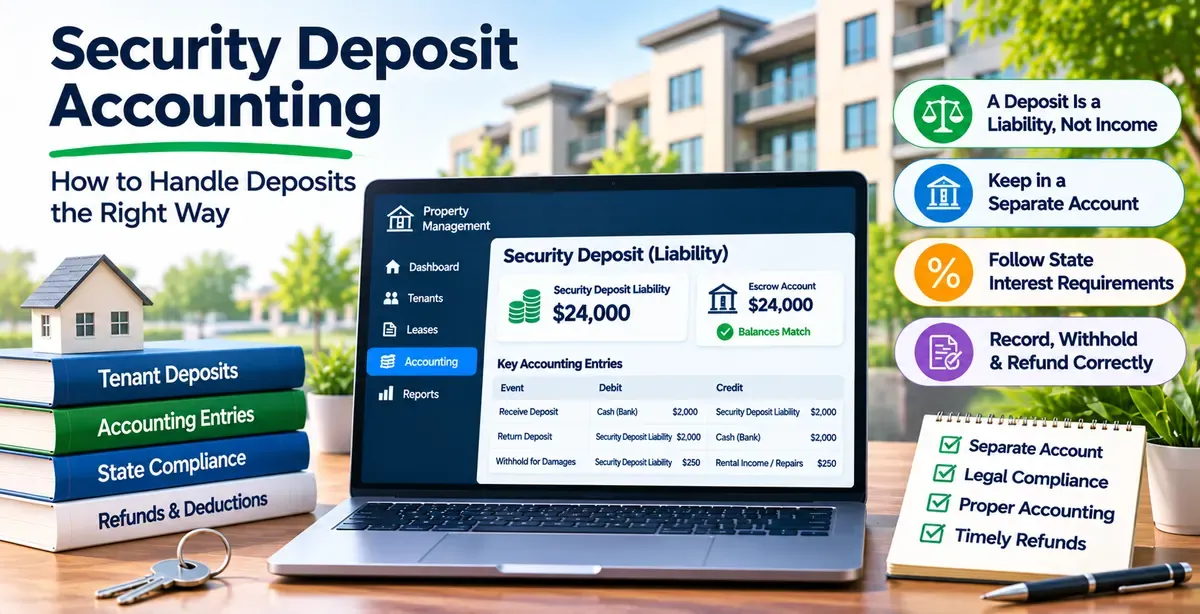
When a tenant pays a deposit, you record it in two places at once. Say a tenant pays a $2,000 deposit:
In double-entry terms, you debit Cash and credit Security Deposit Liability. Revenue is never touched. The deposit shows up as a cash asset in the dedicated account and as a matching liability on the balance sheet.
Throughout the tenancy, the deposit stays on your books as a liability. Nothing about it touches your income, and the balance simply sits there as an obligation you'll eventually settle.
This is also where a simple check protects you. At any given time, the total of all your security deposit liabilities should match the balance in your security deposit account. If those two numbers don't match, something is wrong and needs to be found before it becomes a bigger problem.
When the tenant moves out and you return the full deposit, you reverse the original entry. Cash decreases by $2,000 and the liability decreases by $2,000.
The result is clean: the obligation is gone, and nothing ever hit your income statement. The deposit passed through your books as money you held and then gave back, exactly as it should.
If you withhold part of the deposit for damages or unpaid rent, the accounting shifts. Say a tenant's $2,000 deposit has $250 withheld for a broken window.
You return $1,750 to the tenant, and the remaining liability clears. The $250 you keep is recognized as income (or applied against the repair expense) at that point, because now you've earned the right to it under the lease.
How you record deposits is only half the job. Where you keep the money is the other half, and it's often a legal requirement.
Most states require landlords and property managers to hold security deposits in a separate, dedicated bank account, apart from operating funds and personal money. Roughly half the states mandate this explicitly, and for licensed property managers handling client funds, separate trust accounts are typically required regardless.
Even where the law is silent, keeping deposits in their own account is the right practice. A separate account means the money is physically there on move-out day, your books reconcile cleanly, and an auditor or court can see at a glance that you didn't commingle funds.
About 15 states go further and require the deposit account to be interest-bearing, with the accrued interest paid to the tenant, either annually or at move-out (sometimes minus a small administrative fee). If you operate in one of these states, you need to track and pay that interest correctly.
Some states let you hold all deposits in a single pooled trust account. Others require individual tracking per tenant. Even with a pooled account, you must track each tenant's deposit as a separate liability, so you can always trace every dollar back to a specific lease. This tenant-level tracking is part of a well-structured chart of accounts.
Commingling, mixing security deposits with your operating funds, is one of the most serious mistakes in property management accounting, so it deserves its own warning.
The danger is practical before it's legal. Keep in mind, income "reads" as spendable in your mind; a liability reads as "don't touch." When deposits sit in your operating account, they feel like available cash, and available cash gets spent. Then move-out arrives and the money is gone.
The legal consequences are severe. Courts in nearly every state treat commingling or misappropriating security deposits as a violation that can trigger treble damages (two to three times the deposit) plus the tenant's attorney fees. For licensed property managers, it's also a licensing issue, not just an accounting one.
The fix is straightforward: keep deposit money physically separate from operating cash, and track each deposit as its own liability. Do that, and the commingling risk disappears.
When a tenant moves out, the deposit accounting comes to a head. A few practices keep it clean and compliant.
If you withhold any part of the deposit, you generally must provide the tenant an itemized statement of deductions, backed by documentation (photos, repair receipts). Deductions are for damage beyond normal wear and tear, not for ordinary aging like faded paint or minor carpet wear.
States set strict timelines for returning the deposit or providing the itemized deduction statement, commonly 14 to 30 days after move-out. Missing the deadline can forfeit your right to withhold anything, and trigger penalties.
Legal fees from a deposit dispute far exceed any short-term benefit of holding the money. When a deduction is questionable, returning the deposit is often the cheaper choice.
Everything above is manageable by hand for one or two units. The failure mode isn't misunderstanding the rules; it's the spreadsheet that didn't get updated in month 14, the deposit that got miscategorized, the account that slowly drifted out of balance.
Property management software with real double-entry accounting removes that risk. It records each deposit as a liability from day one, keeps it attached to the specific tenant and lease, and shows deposits held on your reports, so move-out becomes arithmetic instead of archaeology.
Mocha Manage was built by CPAs, so this kind of correct-by-default handling is the foundation rather than an afterthought. Because it's built on real accounting with trust accounting support, the classification you'd otherwise have to remember to do by hand happens correctly on its own.
Here's how the right features keep deposit accounting clean and compliant:
The result is exactly what security deposit accounting should be: accurate, compliant, and boring. Deposits stay separated, the books reconcile, and move-out is a simple, defensible calculation.
Try Mocha Manage free to see how correct deposit accounting works when it's built into the platform.
Is a security deposit income?
No. A security deposit you intend to return is a liability, not income, because the money belongs to the tenant until the lease ends and you have a lawful, documented reason to keep some of it. It only becomes income if you withhold part of it for damages or unpaid rent.
How do you record a security deposit in accounting?
When you receive it, you debit Cash and credit a Security Deposit Liability account for the same amount. The deposit appears as a cash asset and a matching liability on your balance sheet, and never touches revenue until (and unless) you withhold part of it.
Do security deposits have to be kept in a separate account?
In most states, yes. Roughly half explicitly require a separate, dedicated account, and licensed property managers handling client funds are typically required to use separate trust accounts regardless. Even where it isn't required, keeping deposits separate is best practice.
What happens if you commingle security deposits?
Commingling (mixing deposits with operating funds) can trigger severe penalties. Courts in nearly every state allow tenants to recover two to three times the deposit amount plus attorney fees, and for licensed managers it's also a licensing violation.
Do I have to pay interest on security deposits?
It depends on your state. About 15 states require deposit accounts to be interest-bearing, with the interest paid to the tenant annually or at move-out. Check your state's landlord-tenant law to see if this applies.
How long do I have to return a security deposit?
State laws set the deadline, commonly 14 to 30 days after move-out, for returning the deposit or providing an itemized statement of deductions. Missing the deadline can cost you the right to withhold anything and may trigger penalties.
Disclosure: Mocha Manage publishes this blog. This guide is for informational purposes only and does not constitute legal, financial, or accounting advice. Security deposit laws vary significantly by state and locality. Consult an attorney or accountant familiar with your local landlord-tenant law for advice specific to your situation.